Thinking About a Second Home? What New York's New Tax Teaches Every Buyer
New York City's new second-home tax is a reminder that the price is only part of the story. Here's what Colorado second-home buyers should plan for, and how second-home and investment loans differ.
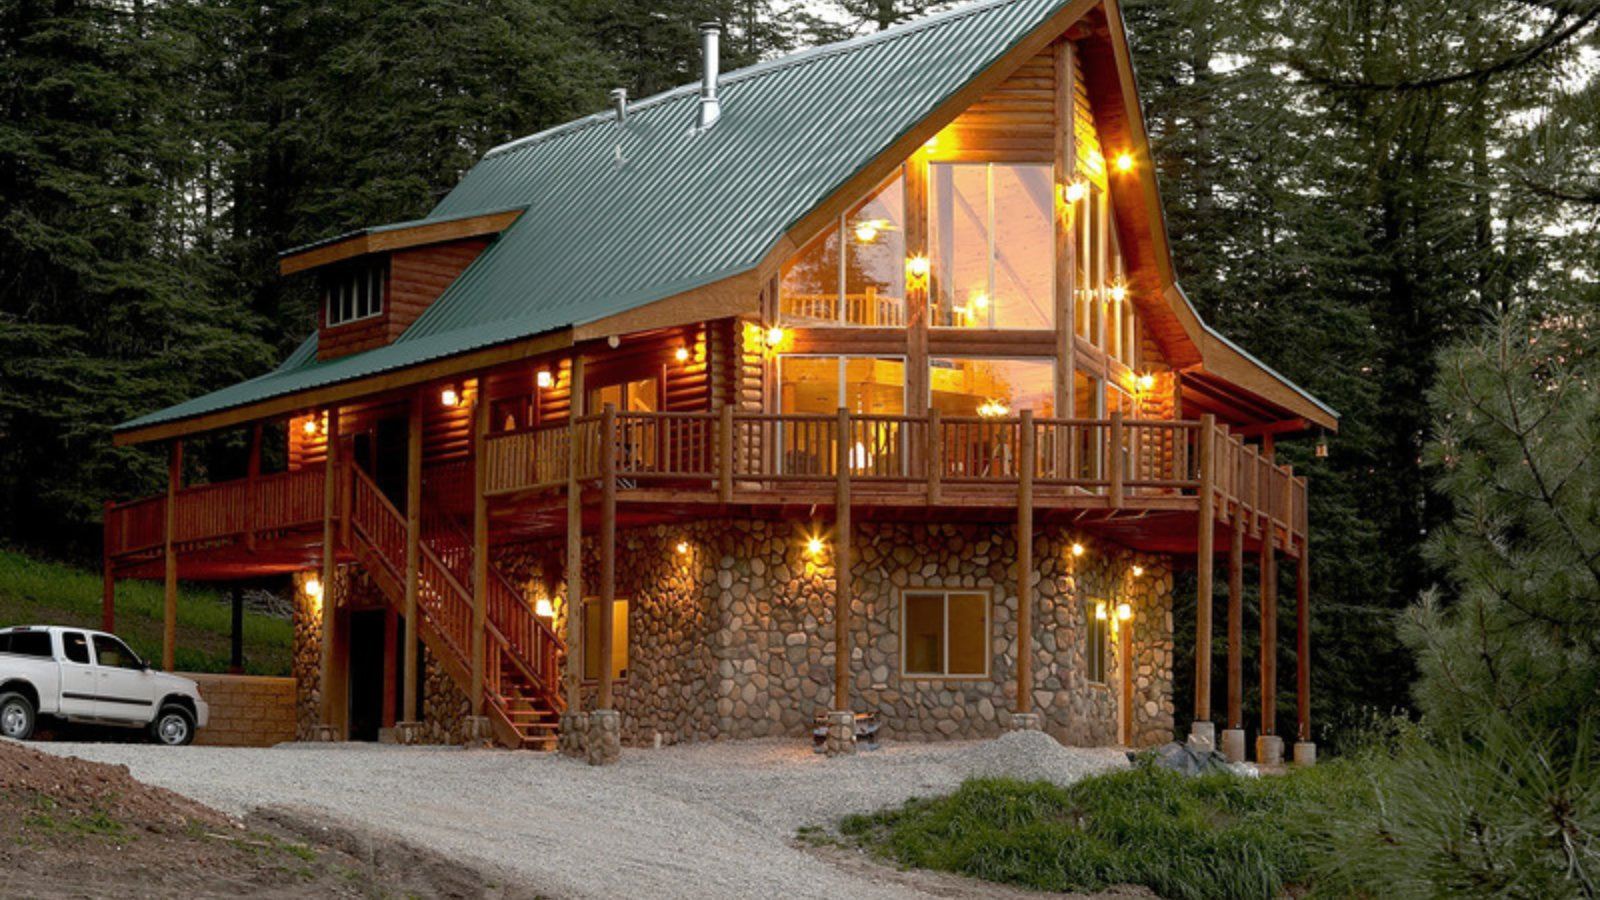
A second home can be a ski condo in Breckenridge, a cabin near Estes Park, or a place closer to the grandkids. Whatever the dream, the purchase price is only part of the story. New York City just gave everyone a reminder of that.
What happened in New York
This year New York created an annual tax on high-value homes in New York City that aren't the owner's primary residence. It's often called the "pied-à-terre tax." For houses, it kicks in above $5 million: the first $5 million isn't taxed, and the value above it is taxed at 0.8% to 1.3% a year, on top of regular property taxes. Condos and co-ops follow a separate schedule for the first two years. The tax started July 1, 2026, and the owner's own primary residence and homes leased long-term to a full-time tenant are exempt.
So far, luxury buyers haven't run for the exits. Manhattan sales above $5 million were roughly flat to slightly up in the months after it passed.
Why this matters if you're buying in Colorado
Most of us will never shop for a $5 million New York apartment. But the lesson applies everywhere: a second home comes with its own yearly costs, and local rules can change after you buy. Before you fall in love with a place, plan for:
- Property taxes and HOA dues in that county and community, not the one you live in now.
- Insurance, which can run higher in mountain and wildfire areas.
- Local rental rules. Many Colorado mountain towns limit or license short-term rentals. If you're counting on rental income, check the town's rules first.
- Travel and upkeep for a home you aren't in every day.
Second home or investment property? The loan depends on it
Lenders treat these two differently, and the difference shows up in your down payment and rate.
- Second home: you use it yourself for part of the year, and it isn't run as a full-time rental. Down payments often start around 10%, and rates are usually close to a primary home's.
- Investment property: you buy it mainly to rent out. Expect a larger down payment and a somewhat higher rate.
How you plan to use the home decides which loan fits, so it's worth talking through before you make an offer.
Thinking about a second home?
We shop more than 100 lenders to find the loan that fits how you'll actually use the place. Take our free Neighborhood Tour of any address, run the numbers with our mortgage calculators, or book a 15-minute call with us. No pressure, just answers.
David & Stephanie Cramm, That Mortgage Couple