VA Home Loans
The VA Loan provides veterans with a federally guaranteed home loan that may not require a down payment. This program was designed to provide housing and assistance for veterans and their families. VA home loans are available in all 50 states, may have reduced closing costs, and have no prepayment penalties.
VA home loans may be available to eligible veterans, active-duty service members, National Guard and Reserve members, and certain surviving spouses. Eligibility depends on service history and other VA requirements.
The VA home loan program began in 1944 through the Servicemen's Readjustment Act, also known as the GI Bill. It was signed into law by President Franklin D. Roosevelt and was designed to help veterans buy homes with a federally guaranteed loan. VA loans are made by private lenders, such as banks and mortgage companies, to eligible borrowers.
VA home loans may be available to eligible veterans, active-duty service members, National Guard and Reserve members, and certain surviving spouses. Requirements depend on when and how long you served, your discharge status, and other VA rules. The VA issues a Certificate of Eligibility to confirm your benefit. Contact us and we'll help you get started.
A VA home loan must be used to finance your personal residence within the United States and its territories. You have choices for the type of home you purchase:
- Existing Single-Family Home
- Townhouse or Condominium in a VA-Approved Project
- New Construction Residence
- Manufactured Home or Lot
- Home Refinances and Certain Types of Home Improvements
- 100% Financing Available for Eligible Borrowers
- No Private Mortgage Insurance (PMI)
- No Penalties for Prepaying the Loan
- Competitive Interest Rates
- Flexible Qualification Guidelines
You can apply for a VA Loan with any mortgage lender that participates in the program. In addition to the application the lender will obtain the following:
- Certificate of Eligibility and Proof of Military Service
Yes, your eligibility is reusable depending on the circumstance. If you have paid-off your prior VA Loan, and disposed the property, you can have your eligibility restored again. Also, on a 1-time basis, you may have your eligibility restored if your prior VA Loan has been paid-off, but you still own the property.
- Some uninformed sellers may be hesitant to work with someone obtaining a VA Loan because they are worried about a buyer who's not putting money down or they are unfamiliar with the VA loan process. However, a strong lender will ensure a seller's agent doesn't fall into these misconceptions.
The funding fee. Most VA loans have a one-time VA funding fee, which can usually be rolled into the loan. Veterans who receive VA disability compensation, and some others, are exempt.
Refinancing. If you already have a VA loan, a VA streamline refinance (IRRRL) can lower your rate with less paperwork. A VA cash-out refinance lets eligible borrowers tap their home's equity.
Using your benefit again. Your VA benefit can often be used more than once, and in some cases you can have more than one VA loan at a time.
What to have ready. Your Certificate of Eligibility (we can request it for you), your DD-214 or a statement of service, recent pay stubs or other income documents, and recent bank statements. We'll tell you what else we need before you pull everything together.
Questions? Call or text (303) 931-6776.
Not all programs are available in every state. All loans are subject to credit approval. Rates, terms and conditions vary by program.
Stephanie Cramm, NMLS #243972 | David Cramm, NMLS #565968 | Xpert Home Lending, Inc. NMLS #2179191 | Equal Housing Lender
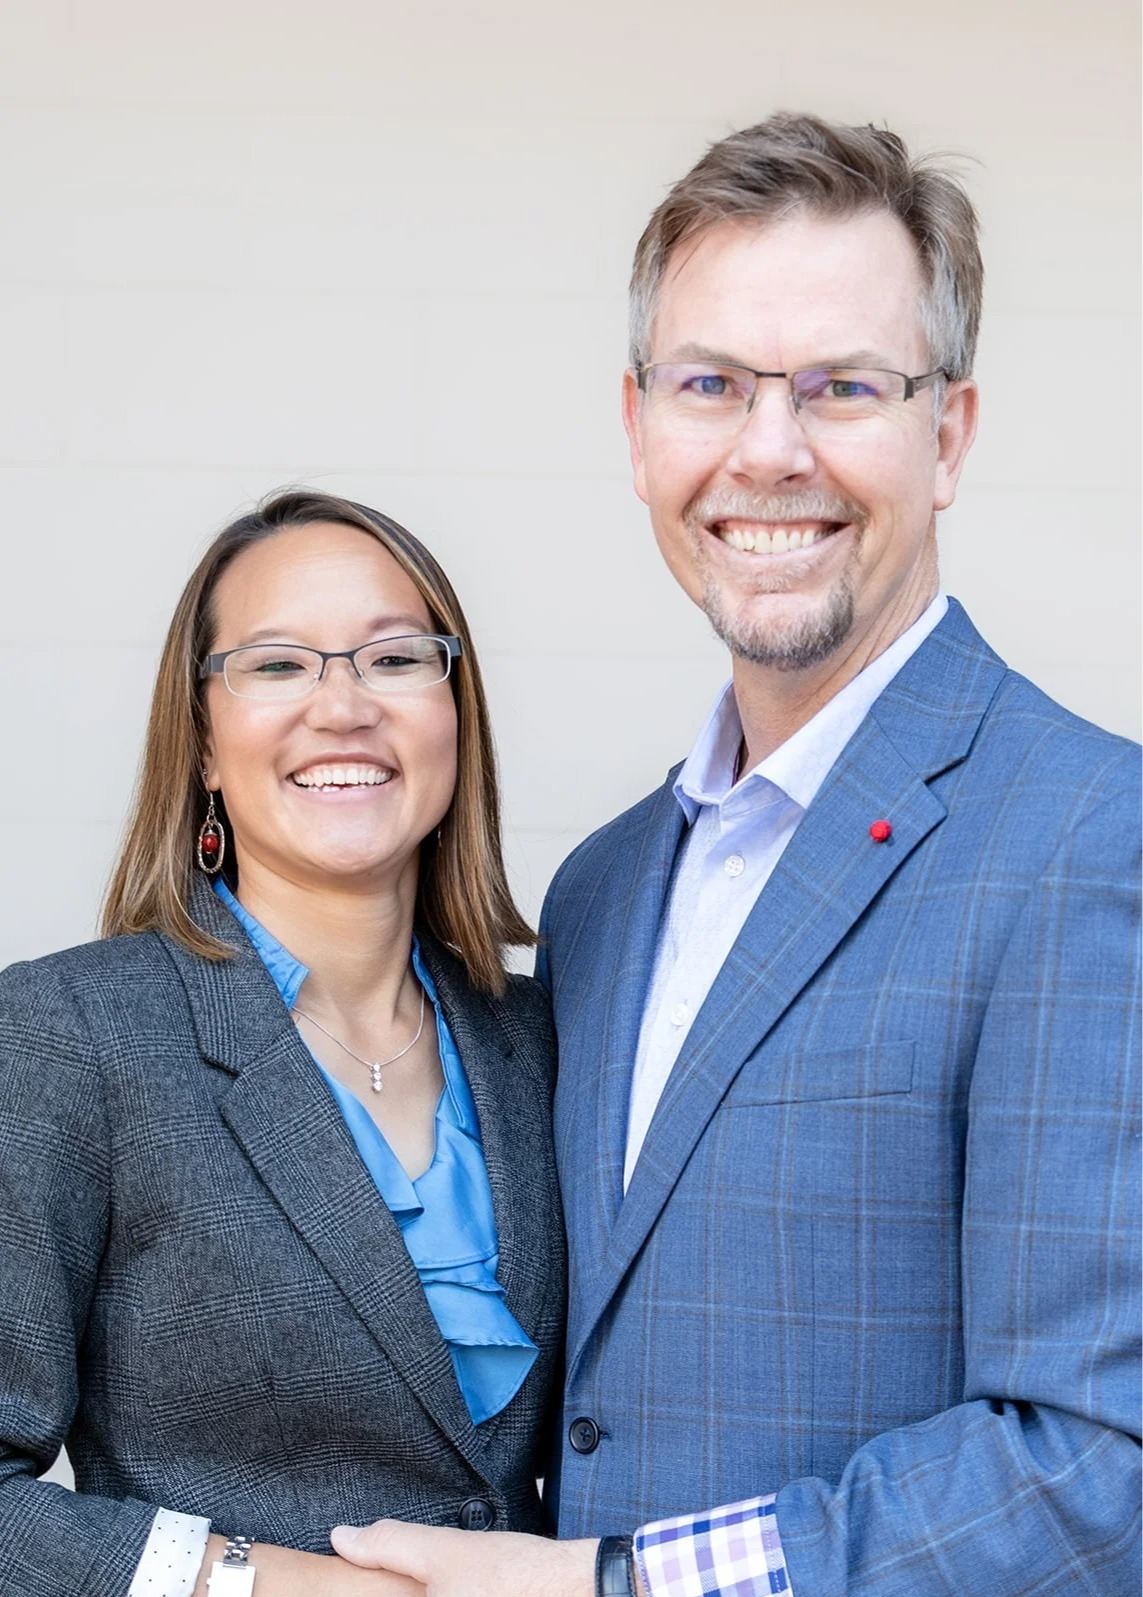
Talk with Stephanie & David
We're a husband-and-wife mortgage broker team. We'll walk you through your VA benefit, then shop 100+ lenders to find the right fit.